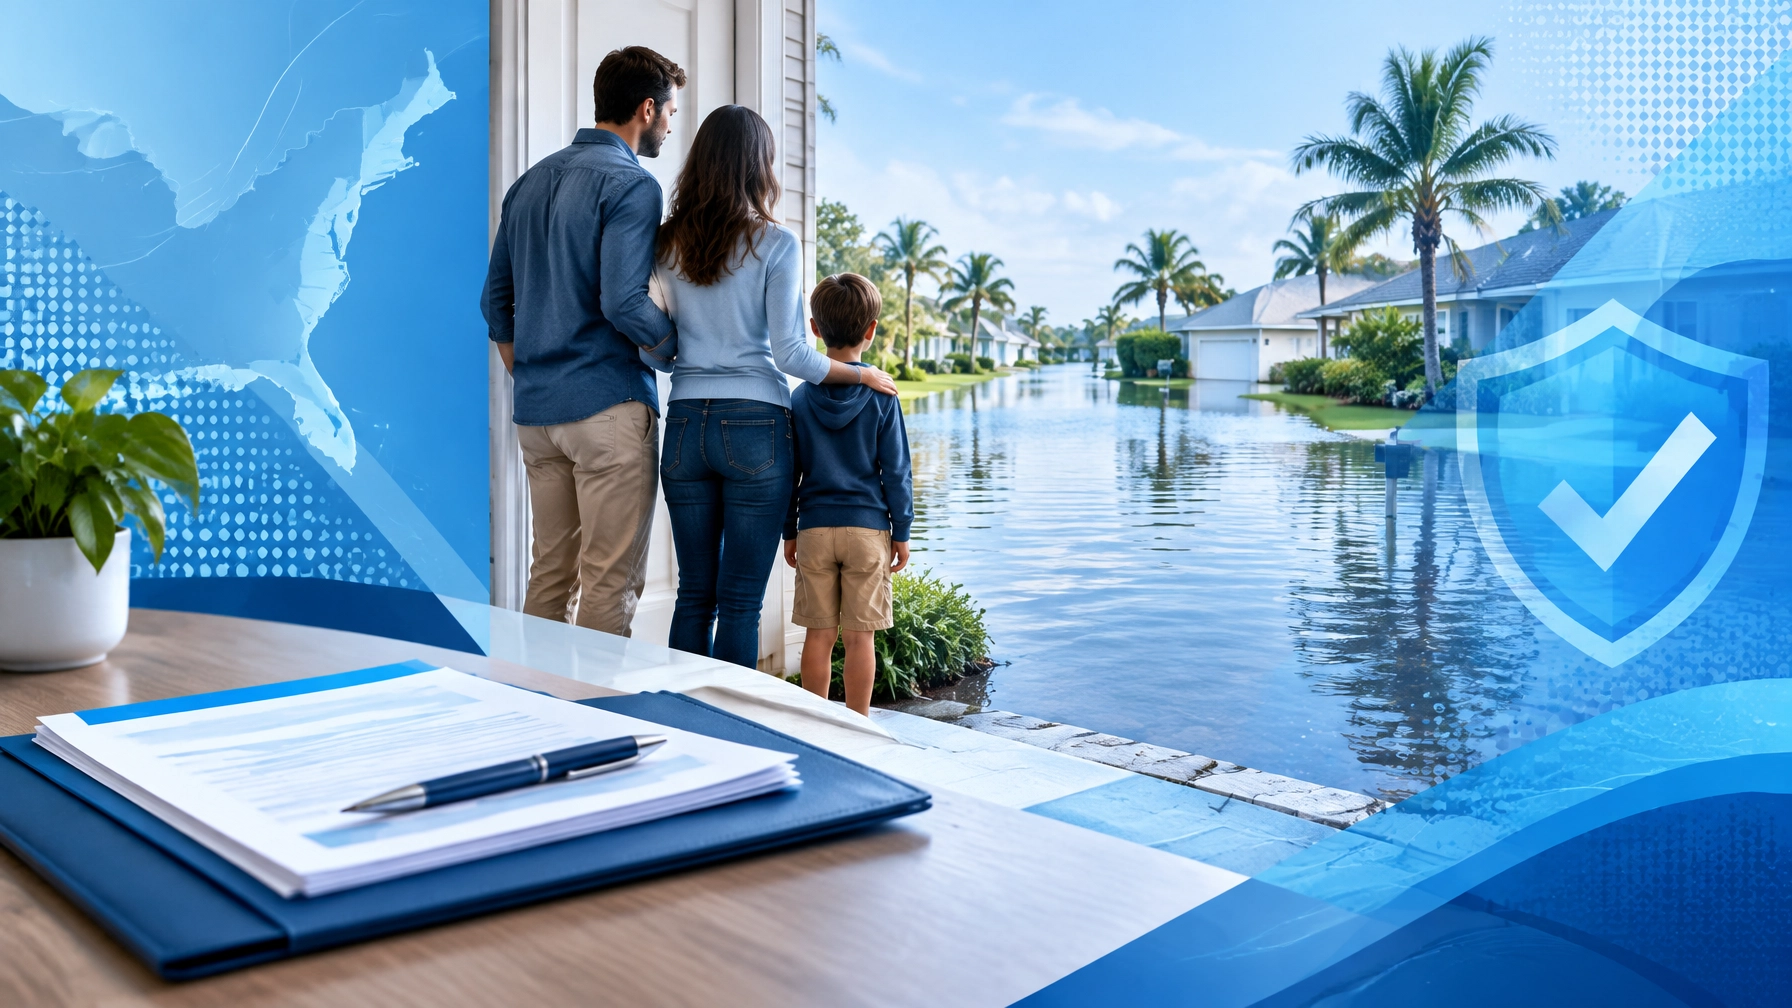
Flood insurance is the gap behind this weekend's California and Florida flooding, and a 30-day waiting period is why most homeowners cannot close it now.
What the November 21 Storm Update Changed
The Associated Press reported on November 21 that scattered rain continued to worsen historic flooding across central Florida as Northern California braced for a major deluge during high tides before Thanksgiving travel week. San Francisco Mayor Daniel Lurie described the forecast as “extremely serious” and urged people to consider avoiding holiday travel. The Associated Press report said forecasts called for unusually high tides and possible flooding in low-lying shoreline areas.
In Florida, the AP reported that the St. Johns River continued to rise after heavy rain, including near Cocoa, where it exceeded a 1953 record. The weather service expected river flooding to continue for an extended period, even if heavier rain had passed.
Analysis: The storms are a timely reminder that a flood insurance decision cannot be made in response to a forecast and still cover damage from that same event. A new policy generally has a waiting period. The practical effect is that flood coverage is for the next storm, not the one already underway.

Two Illustrative Households
These examples are illustrative and do not describe real named individuals.
A homeowner in Geneva, Florida, near the St. Johns River in Seminole County, has an active standard homeowners policy but no flood policy. If rising river water floods the home, the standard policy generally does not cover that flood damage. The homeowner can document damage safely, contact the homeowners insurer about any separate covered damage, and ask about future flood coverage. A new flood policy cannot cover this event.
A renter in a low-lying San Francisco neighborhood has no flood policy, and the landlord’s policy does not cover her belongings. The landlord’s building coverage does not substitute for coverage on a tenant’s personal property. She can document belongings, check whether her renters policy covers a separate cause of water damage, and ask about flood contents coverage for future events. Buying flood insurance now cannot cover damage from this storm.
Why a Standard Homeowners Policy Does Not Pay for This
Does homeowners insurance cover flood damage? Most standard homeowners and renters policies exclude damage caused by flooding. Wind-driven rain may be covered under some policies, depending on the cause of the damage and the contract terms. Damage caused by fallen trees is generally covered under standard homeowners policies, subject to policy conditions.
Auto coverage is separate. Comprehensive coverage can cover vehicles damaged by flooding or fallen trees. Check the declarations page to see whether comprehensive coverage is already included. Adding coverage after a warning may be possible for future losses, subject to the insurer’s terms and effective date. It does not cover damage that has already happened.
The practical distinction is that wind-driven rain, fallen trees, and comprehensive auto coverage may already be part of a current policy or may be available for future events. Flood coverage usually cannot begin immediately. No policy change provides retroactive coverage for a loss that has already occurred.
The 30-Day Wait and the December 11 Deadline
FEMA says flood policies typically have a 30-day waiting period from purchase to the start of coverage, with exceptions. A policy bought on Sunday, November 22, 2026, would generally take effect around Tuesday, December 22, after the current NFIP authorization deadline.
FEMA says Congress must reauthorize the NFIP by 11:59 p.m. on December 11, 2026. If authorization lapses, FEMA would stop selling and renewing policies. FEMA also says it would retain authority to pay valid claims with available funds, and that existing NFIP contracts have not gone unhonored. A lapse would not itself cancel policies already in place. FEMA’s reauthorization notice also cites an estimate that a lapse could affect about 1,300 property sales each day.
The dates show how the two issues interact:
- November 22: A policy purchased on this date would generally take effect around December 22, after the current authorization deadline.
- December 1: A policy purchased around this date would generally reach its 30-day start date around December 31.
- December 11: The current NFIP authorization ends at 11:59 p.m. unless Congress renews it. A lapse would stop new sales and renewals.
- After December 11: If a lapse occurs, a household waiting to buy could find that new NFIP policies are not available until authorization resumes. Holiday schedules may add practical delays.
Analysis: Buying before December 11 keeps the purchase within the current authorization period, but the 30-day wait means not every purchase made before that deadline will be in force before the end of December. A purchase around December 1 would generally reach its start date around December 31; a later purchase would take effect later. Households considering coverage should ask an agent when a policy would actually begin and whether any waiting-period exception applies. The timing makes the calm months, including late November through early spring, the practical flood-buying season. Waiting for a named storm can mean waiting too long for that event.

What an NFIP Policy Actually Pays, and What It Leaves Out
NFIP building and contents coverage are purchased separately and have separate deductibles. Building coverage applies to the physical structure, including electrical and plumbing systems, permanent interior features, utility-related items, and certain detached garages. Contents coverage applies to personal belongings, portable appliances, laundry appliances, and certain fixtures.
For most residential NFIP policies, the maximum building coverage is $250,000 and the maximum contents coverage is $100,000. These limits may not cover a home’s full repair or replacement costs. Contents are generally covered for their actual cash value at the time of damage, not their original purchase cost; NFIP contents coverage does not provide full replacement value.
NFIP building and contents coverage generally exclude living and financial costs, outdoor property, most vehicles, some valuables, and damage that could have been avoided. Policy terms and exclusions matter. Review the NFIP coverage information and confirm specific items and limits in the policy documents.
Analysis: Depreciated contents value is a potential gap that may only become clear at claim time. A household with a heavily furnished home should compare the policy’s actual-cash-value terms and contents limit with the amount of property it would need to replace. NFIP rates do not vary between companies or agents; NFIP policies are sold through participating insurers and independent agents. Private flood insurance may have different pricing and terms.
The Wildfire Burn-Scar Exception in California
California homeowners, renters, and commercial policies typically exclude damage caused by flooding, mudslides, and debris flows. The California Department of Insurance says exceptions may apply when damage is directly or indirectly caused by a recent wildfire or another covered peril. The department has also reminded insurers of their duty to cover damage from mudslides, debris flows, or similar disasters caused by wildfires that may have weakened hillsides.
The California Department of Insurance notice says renters should review their own policies because a landlord’s insurance generally does not cover a tenant’s belongings. It also advises checking auto declarations for optional comprehensive coverage. Coverage depends on the facts and policy language; a wildfire-related exception should be confirmed with the insurer.
What to Ask a Flood Insurance Agent, in Writing
Flood insurance cost depends on property and coverage details. A written response can help record what was reviewed and what remains subject to confirmation.
- What flood zone is recorded for the property, and could an elevation certificate change the premium?
- If the property is in a moderate-to-low risk area, does a preferred risk policy apply?
- Would private flood coverage provide higher limits or broader coverage than NFIP maximums? How do its waiting period and contents valuation compare with NFIP actual cash value?
- Does the homeowners policy cover wind-driven rain or fallen trees? In California, how does it address mudslide or debris-flow damage caused by a recent wildfire?
- Does the auto policy include comprehensive coverage?
- How are the basement, crawlspace, and detached garage treated under the proposed policy?
- What are the building and contents deductibles, stated separately?
- What date would coverage begin if the policy is purchased now, and does a waiting-period exception apply?
Checking a Flood Insurance Agent's License
Flood policies are sold through licensed insurance agents. Since NFIP rates do not vary by company or agent, the comparison is not an NFIP price comparison. License status and, where applicable, authorization to sell the relevant coverage are details to confirm.
Ask for the agent’s name, National Producer Number (NPN), and the states in which the agent is licensed. License records can be reviewed through the state-based VerifiedAgent lookup. The record is a directory resource; current license and appointment status should be independently confirmed with the relevant state regulator or insurer.